Walk into most UAE bank branches on a AED 4,000 salary and ask for a credit card, and you’ll usually hit the same wall: “minimum income is AED 5,000.” That line is repeated so often that most people give up before checking whether it’s actually the full picture.
It isn’t. Banks don’t approve or reject purely on the printed salary number — your AECB score, your banking relationship, and the type of card you’re applying for all matter just as much. If you’re specifically looking for a 4000 salary credit card in the UAE, understanding how those pieces fit together is what actually gets you approved, not memorizing a salary cutoff.
Quick Answer: A 4000 salary credit card is unlikely through a standard unsecured application in the UAE — most banks set AED 5,000 as the baseline. But you can still get a real, usable credit card through a secured (deposit-backed) card, a payroll-based relationship with your salary bank, or select entry-level digital cards. Your AECB score matters here as much as your salary does.
How to Get a 4000 Salary Credit Card in the UAE
Getting approved at this income level comes down to reducing the bank’s risk in one of three ways: putting up collateral, giving the bank visibility into your finances through payroll, or applying for a product built for lower income brackets. Here’s how each actually works.
Why UAE Banks Set a AED 5,000 Minimum Salary
Credit cards are unsecured lending — if you default, the bank has no collateral to recover the loss. Banks use salary as the simplest proxy for repayment ability, and AED 5,000 is roughly the point where, after rent, transport, and daily expenses, there’s enough margin left to service a monthly credit card bill without high default risk.
This threshold isn’t set by federal law — it’s each bank’s internal risk policy, shaped loosely by Central Bank of the UAE (CBUAE) consumer lending guidance, which caps how much unsecured debt a bank can extend relative to income. That’s also why the number varies slightly bank to bank instead of being a single fixed rule — but search the minimum salary for credit card UAE requirements across any major bank, and AED 5,000 comes up as the consistent starting point.
Your AECB Score Matters as Much as Your Salary
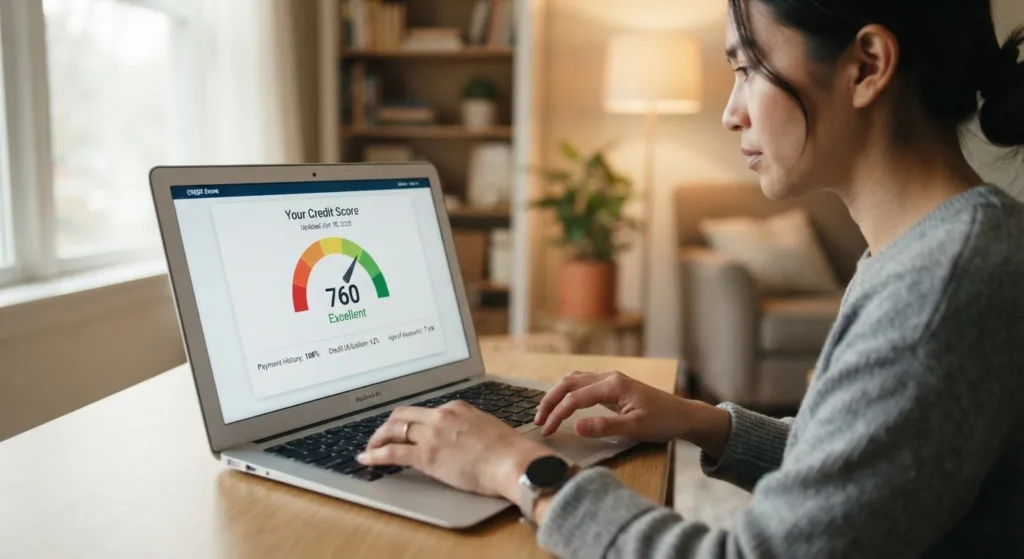
This is the part almost no comparison site explains clearly. Every credit application in the UAE runs through the Al Etihad Credit Bureau (AECB), which generates a credit score between 300 and 900 based on your repayment history, existing debt, and credit utilization.
A salary of AED 4,000 with a clean AECB score above 650 is often a stronger application than a salary of AED 6,000 with missed payments or high utilization on an existing loan. If you’ve never had credit in the UAE, your file may simply be thin rather than bad — which is exactly what a secured card is designed to fix.
Understanding your AECB score for credit card approval before you apply — not after a rejection — is one of the simplest ways to avoid wasting an application. You can check your own AECB score directly through the AECB website or app for a small fee before applying, so you’re not applying blind.
Option 1: Secured Credit Cards — The Most Reliable Route
A secured credit card UAE application flips the usual approval logic. Instead of the bank assessing your salary as the main risk factor, you place a fixed deposit with the bank, and your credit limit is set as a percentage of that deposit — typically in the 80–100% range, though the exact ratio and minimum deposit vary by bank and change over time, so confirm current terms directly with the bank before applying.
| Bank (indicative) | Typical Minimum Deposit | Notes |
|---|---|---|
| Emirates NBD | From ~AED 10,000 | Lower entry deposit than most major banks; strong digital onboarding |
| RAKBANK | From ~AED 15,000–25,000 | Known for serving first-time and lower-income borrowers |
| Mashreq | From ~AED 10,000–15,000 | Digital-first application via Mashreq Neo |
| ADCB | From ~AED 10,000–20,000 | Stronger approval odds if salary is also transferred here |
Figures above are indicative starting ranges based on general fixed-deposit minimums, not official secured-card policy — banks don’t always publish exact deposit-to-limit ratios, so treat this as a starting comparison and confirm current numbers with the bank directly.
Why This Option Works
Because the bank holds your deposit as collateral, your salary becomes a secondary factor rather than the deciding one. You get a real, functioning credit card — not a prepaid card — and every on-time payment builds your AECB history, which is what eventually qualifies you for an unsecured card later. The only real cost is that your deposit stays locked while the card is active.
Option 2: Apply Through Your Salary-Transfer Bank
When your salary is credited directly into an account at a specific bank, that bank can see your actual cash flow, savings pattern, and overdraft history — data an outside bank never sees from a salary certificate alone. This internal visibility sometimes leads to approval for a small-limit starter card even slightly below the bank’s advertised threshold.
This route isn’t advertised, which is exactly why it’s underused. If you’re chasing a 4000 salary credit card and haven’t asked your own bank yet, this is the first call to make. Visit your salary bank’s branch in person, rather than applying online (if your salary bank is FAB, our guide to registering for FAB online banking is a good first step to see your account activity before you go in), and specifically ask about “entry-level” or “payroll-based” credit cards — a relationship officer can often see approval paths that the online application doesn’t offer.
Option 3: Entry-Level and Digital Cards Worth Trying
A handful of digital-first cards evaluate account behavior — balance history, transaction consistency — alongside salary, rather than applying a hard cutoff. These generally come with modest limits and no annual fee, and they’re worth trying specifically because their underwriting tends to be more flexible than a traditional branch application. Maintaining a healthy balance in the account for a few months before applying meaningfully improves your odds.
If you’re self-employed or between formal payroll, you’re not out of options. Freelancers and business owners typically apply for a credit card without salary certificate UAE requirements by submitting a trade license and 6 months of bank statements instead — several digital banks accept this route directly.
Documents You’ll Need
Whether you’re applying for a secured card, a payroll-based card, or any other 4000 salary credit card option, the paperwork banks ask for is largely the same:
| Document | Why It’s Needed |
|---|---|
| Emirates ID (original + copy) | Identity and residency verification |
| Passport copy with valid visa | Residency status confirmation |
| Latest salary certificate | Confirms employer and income |
| Bank statements (last 3–6 months) | Shows cash flow and repayment capacity |
| AECB credit report (optional, self-pulled) | Lets you check your score before applying |
Step-by-Step: How to Apply for a 4000 Salary Credit Card
- Check your AECB score first. Know where you stand before a bank pulls your file.
- Start with your salary bank. Visit a branch in person and ask about payroll-based entry cards.
- If declined, apply for a secured card. Compare deposit minimums across 2–3 banks before committing funds.
- Gather documents in advance. Incomplete applications are a common cause of delay, not just rejection.
- Avoid applying to multiple banks simultaneously. Repeated rejections within a short window can lower your AECB score.
- Build 3–6 months of clean statements if your first attempt is declined, then reapply.
If You’re Rejected: Real Alternatives
A declined 4000 salary credit card application isn’t the end of the road. A few practical alternatives:
- Supplementary card: If a spouse or family member holds a card, you can be added as a supplementary cardholder — this doesn’t depend on your own salary at all.
- Buy Now, Pay Later apps (Tabby, Postpay, Spotii): not a credit card, but they extend small short-term credit lines for online and in-store purchases without a salary threshold. Useful for cash-flow management, not for building AECB history.
- Reapply after building your file. A secured card held for 6–12 months with clean repayment is often the fastest legitimate path to an unsecured card afterward.
If a secured card or salary transfer route still isn’t working out, it’s worth comparing where you actually stand — see our breakdown of the average salary in Dubai by experience level to know how close you are to the AED 5,000 mark most banks look for.
Not ready for a full credit card yet? A Ratibi card or prepaid salary card can cover everyday spending and online payments in the meantime without any salary threshold at all.
None of these paths guarantee approval, but they reflect how banks in the UAE actually evaluate applicants — not just the number on a salary certificate. Whichever route you take, treat a 4000 salary credit card as a tool for building credit history responsibly, not as extra spending power.
Frequently Asked Questions
Can I get a credit card with a AED 4,000 salary in the UAE?
Not through a standard unsecured card at most banks, but yes through a secured deposit-backed card, a payroll relationship with your salary bank, or select entry-level digital products.
What is the minimum salary for a credit card in the UAE?
Most banks set AED 5,000 as the baseline for standard unsecured cards, though this varies by bank and card type.
Does my AECB score matter more than my salary?
It can. A strong AECB score with a lower salary is often viewed more favorably than a higher salary with a poor repayment history.
What is a secured credit card?
A card backed by your own fixed deposit with the bank. Your credit limit is set as a percentage of that deposit, which lowers the bank’s risk and makes salary less critical to approval.
Does applying to multiple banks at once hurt my chances?
Yes. Frequent applications and rejections in a short period can lower your AECB score and signal higher risk to future lenders.
Can freelancers or self-employed residents apply?
Yes, but they typically need to submit a trade license and 6 months of bank statements showing consistent income instead of a salary certificate.
How long does approval usually take?
Typically 2–7 working days after all documents are submitted, though secured cards can sometimes be faster since underwriting is simpler.
Is a credit card a good idea on a low income?
Only if you pay the balance in full each month. On a AED 4,000 salary, a credit card should be used to build credit history and cover emergencies — not as extra spending power.
What’s the fastest way to qualify for a 4000 salary credit card?
Start with your own salary-transfer bank and ask about payroll-based entry cards in person — it’s usually faster than a secured card application and doesn’t require locking up a deposit.